Chapter 3 - The Midnight Ledger
The first click was the smallest.
I cancelled the pending tuition draft to New York University.
The screen didn't flash red or make a dramatic sound. The status bar simply changed from Pending Processing to CANCELED BY TRUSTEE. A small auto-generated notification was queued to be sent to the university's financial aid office at the start of business hours on Monday morning.
Reason for Cancellation: Beneficiary non-compliance with Section 4(c) of the Arthur Vance Irrevocable Trust Agreement.
Section 4(c) was a clause I had drafted myself at Dad's insistence: All disbursements for higher education are contingent upon the beneficiary maintaining personal conduct reflecting credit upon the family estate, including freedom from active civil litigation or intentional property destruction.
Next, I opened the file for the Soho loft lease.
The lease was held in Mia’s name, but because she had zero income and an unsatisfactory credit score, the landlord—a corporate management group in Midtown—had required a corporate guarantor. The trust served as the primary guarantor, but the secondary personal guarantor was me.
I pulled up the guarantor amendment portal.
With three clicks, I executed a formal Notice of Guarantor Withdrawal based on the beneficiary's breach of lease conduct covenants. Because the lease was up for its annual renewal in precisely fourteen days, the management company's automated risk portal immediately generated a red flag.
Without a guarantor, Mia’s lease would convert to a day-to-day occupancy violation on the first of the month, triggering an automated notice to vacate within thirty days unless a cash deposit equal to six months' rent—$25,200—was deposited into their escrow account.
"That's her loft," Nathan said softly, sitting down in the chair beside me. "Where is she going to go?"
"She has a mother," I replied without looking up. "The same mother who thinks her behavior is just 'processing.'"
Now came my mother's financial structure.
Evelyn Vance lived in a four-bedroom colonial house in Connecticut—a house with a manicured lawn, a heated swimming pool, and an annual property tax bill of $22,400.
She believed the house was fully paid off.
It was not.
When Dad died, the house carried a remaining primary mortgage of $110,000. To prevent Mom from being forced to downsize, the trust had taken out a specialized intra-family loan structure: the trust paid the bank directly every month, and Mom was issued a "maintenance allowance" of $6,500 on the fifteenth of every month to cover groceries, utilities, country club dues, and personal expenses.
The money didn't come from a magical vault. It came from the liquid dividend yields of the primary investment portfolio—a portfolio that I personally managed, rebalanced, and voted shares for every quarter.
I pulled up the monthly allowance schedule.
I lowered the monthly discretionary allowance from $6,500 to the statutory minimum required by the secondary codicil of Dad’s will: $1,200 per month—the exact amount needed to cover basic state health insurance and basic groceries at a non-luxury market.
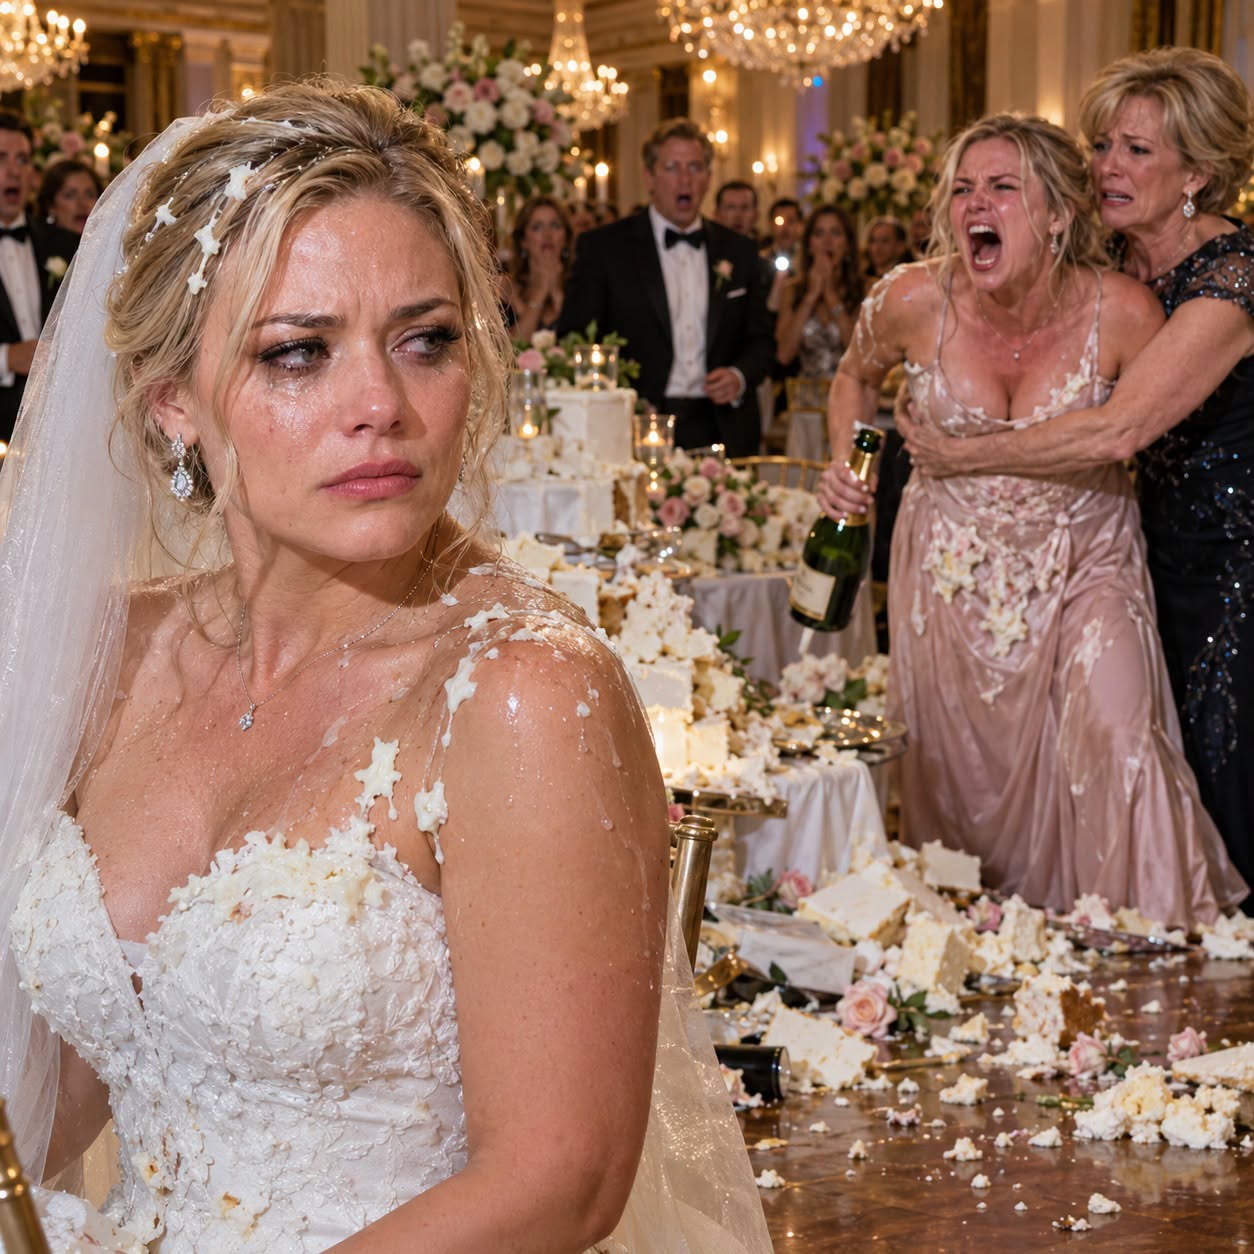
Reason for Reduction: Reallocation of liquid capital to offset un-budgeted property damages incurred at St. Regis Event on October 14th.
I entered the itemized losses manually:
Patisserie Replacement Value: $6,800 Vera Wang Couture Restoration/Loss Fee: $14,000 St. Regis Floor Cleaning & Glass Hazard Fee: $3,200 Linen Destruction Liability: $1,400 Total Offset Amount: $25,400
Until the $25,400 was fully recovered by the trust portfolio, my mother’s monthly allowance would remain at $1,200.
It would take eighteen months of minimal payouts to cover the cost of Mia’s ten seconds of champagne-fueled theater.
Finally, I opened the corporate card portal for Vance & Associates Legal Consulting—my personal firm account through which I had issued secondary credit cards to both Mom and Mia for "emergency family logistics."
Mia’s card limit: $5,000. Current balance: $4,812.90 (mostly spent on hair extensions, boutique shoes, and brunch bills at the Standard Hotel).
Mom’s card limit: $10,000. Current balance: $8,940.00 (including the pending Cabo San Lucas flight deposits).
I selected both cards on the administration dashboard.
I clicked Revoke Cardholder Privileges Immediately.
A warning box popped up on the high-resolution screen:
CRITICAL ACTION: Revoking privileges will immediately terminate active card authorizations and decline any pending settlements that have not yet cleared the clearinghouse. Are you sure you wish to proceed?
I didn't hesitate. My finger clicked CONFIRM.
Across the state, inside Mia’s purse resting on my mother’s passenger seat, and inside Mom’s designer leather wallet sitting on the hall table of her Connecticut house, two black American Express cards instantly became worthless pieces of plastic.
I looked at the digital clock at the bottom right of my screen.
3:14 AM.
The mechanical work was complete. The wires were cut. The dams were closed. The infrastructure that had silently supported two parasites for three years had been quietly dismantled while the city slept around us.
Nathan took my hand, lifting it to his lips to press a warm kiss against my knuckles.
"How do you feel?" he asked softly.
May you like
I looked out the window at the endless grid of yellow lights stretching toward the Hudson River.
"I feel," I said, leaning my head against his shoulder, "like a woman who finally cleared her desk."