Chapter 1 - The Anatomy of a Fracture
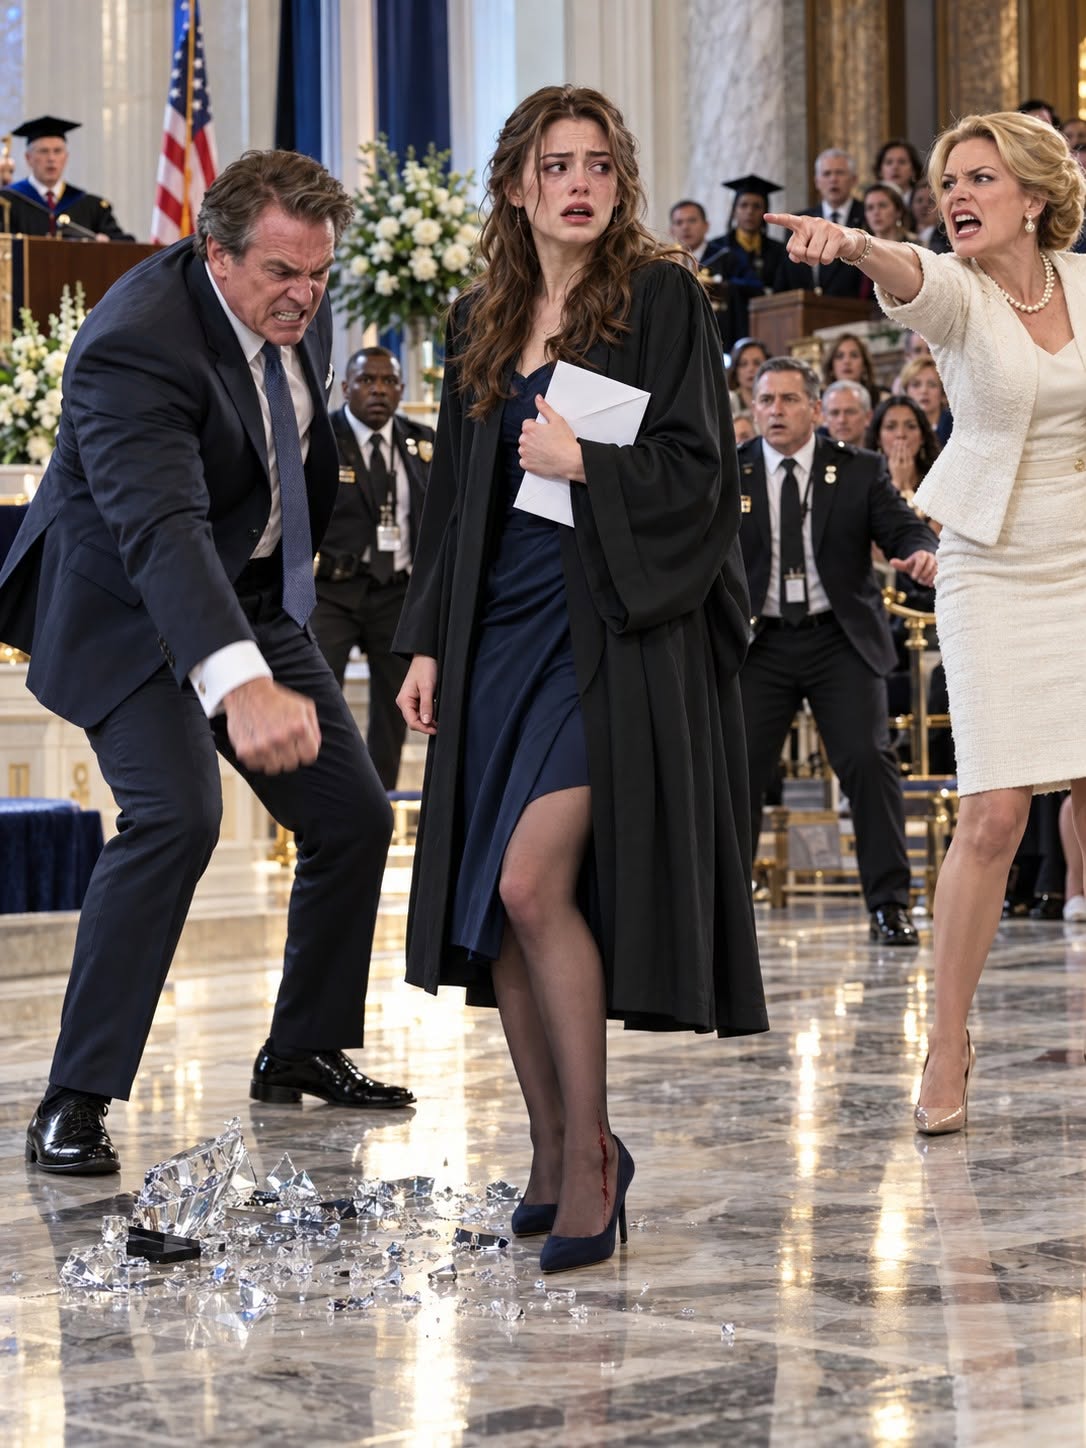
The blood on my ankle had dried into a stiff, rust-colored crust against the weave of my torn sheer tights. When I peeled the nylon away in the bathroom of my Midtown apartment, it took a thin layer of skin with it. I hissed through my teeth, gripping the porcelain edge of the sink until my knuckles went white, watching the red spiral down the drain under the cold tap water.
I didn’t reach for a fancy ointment. I used generic hydrogen peroxide that fizzed aggressively on contact, biting into the jagged trench where a flying wedge of leaded crystal had embedded itself before clattering across the auditorium floor.
The pain was clean. It was physical, measurable, and entirely devoid of emotional ambiguity.
I liked measurable things. That was why I spent sixty hours a week at Carter & Vance Valuation Partners, tearing through commercial leases, analyzing discounted cash flows, and cross-referencing public tax records with private debt schedules. When an asset was insolvent, the balance sheet didn’t scream at you or tell you that you were selfish; it simply produced a negative number in parenthetical red ink.
My phone, resting face-up on the laminate vanity beside an open box of gauze pads, buzzed with rhythmic, violent persistence.
DAD: You embarrassed this family. DAD: Apologize to your mother. DAD: We need to discuss something important this weekend. Be available.
I didn’t reply. I didn’t swipe the notifications away. I wrapped my ankle in two layers of sterile dressing, secured it with medical tape, and walked with a stiff, careful gait into my small living room.
On my kitchen island sat the white linen envelope from the university. Inside was a cashier’s check drawn on a regional commercial bank, made out to Sloan Monroe in the exact amount of $20,000. It was signed by the university provost and the chair of the graduate business endowment.
Twenty thousand dollars.
To Fallon, that was four trips to the designer showrooms in Miami or a down payment on the custom bronze display cases she had insisted on importing from Milan for her boutique. To my father, it was a rounding error on an executive bonus he hadn’t seen since his mid-tier logistics consultancy began losing contracts four years ago.
To me, it was precisely $19,420 of principal debt across two lingering federal consolidation loans, plus interest through the coming Tuesday.
I opened my laptop, typed in the secure gateway address for my student loan servicer, and stared at the balance: $19,384.12.
My finger hovered over the trackpad. For four years—through sixty-hour work weeks, through microwaved bean burritos eaten over spreadsheets, through two levels of the CFA exam passed on three hours of sleep a night in drafty library corners—this number had sat on my chest like a lead weight. Every time my father made a snide remark about my "cheap little car" or my mother asked why I couldn't afford to contribute three hundred dollars to Fallon’s birthday spa weekend in Sea Island, this balance had been the silent warden holding me in my place.
I entered the routing number. I entered the account number. I typed the full balance into the payoff field.
Confirm transaction? This action cannot be reversed.
I clicked Confirm.
The screen refreshed. A green banner bloomed across the top of the browser: Account Balance: $0.00. Loan Status: Paid in Full.
A shudder ran through my diaphragm, sharp and unexpected. I had imagined this moment a thousand times. I had thought I would cry, or laugh, or call someone. But there was no one to call. My parents had spent the afternoon trying to have me criminally charged with disorderly conduct because my bleeding ankle had made a scene in front of their country-club acquaintances, and Fallon was undoubtedly at an upscale steakhouse in Buckhead, nursing a dry martini while Grady stroked her hand and told her that her sister was an unhinged, jealous sociopath.
I closed the browser window. My checking account still held $615.88—the remainder of the prize money after the payoff, plus my remaining paycheck buffer.
I was broke. But for the first time since my eighteenth birthday, I did not owe a single cent to any institution or human being on earth.
I pulled open my work email to log my off-hours billable time, but an unread message in my personal inbox caught my eye. It was from the automated notification portal of the Fulton County Superior Court Clerk’s public records repository.
Three days ago, as part of my day job reviewing commercial portfolios in the urban enterprise zone, I had run a title and encumbrance search on a three-story brick-and-timber property on Howell Mill Road—the building that housed Fallon’s Closet, my sister’s failing luxury boutique.
I had initiated the search routinely, thinking it might be a useful comparative sale for a retail appraisal I was writing for an institutional lender. But the county record alert hadn't returned a simple property card. It had returned an omnibus index linking the parcel to a newly recorded statutory deed of trust, an associated UCC fixture filing, and a private corporate registry entry that I hadn't seen before.
The owner of the Howell Mill building was listed as Highland Ridge Holdings LLC.
And the primary registered agent for Highland Ridge Holdings LLC was not a developer, an investment trust, or an institutional bank.
The agent was Graham Monroe. My father.
The secondary signatory on the corporate charter was my mother, Rowena Monroe.
I frowned, leaning closer to the screen. My father had claimed for five years that he had retired from his consulting firm with a modest annuity. He had complained incessantly about the cost of living, using his supposed fixed income as an emotional cudgel whenever I asked why they had paid for Fallon’s four-year stay at an out-of-state private college while refusing to co-sign a $3,000 promissory note for my undergraduate textbooks.
“We don't have it, Sloan,” he had told me over the phone when I was nineteen, working the graveyard shift at a distribution hub in Doraville while studying microeconomics during fifteen-minute break intervals. “Every dime we have is tied up in our retirement security. You're strong. You have resilience. Fallon is delicate; she needs a safety net. You don't.”
I clicked on the instrument number for the Highland Ridge filing.
A forty-two-page PDF document opened. It was a certified copy of a private collateralized promissory note, recorded six months earlier, securing a loan of $600,000 against the unencumbered fee-simple title of my late grandmother’s house in Savannah.
My grandmother, Clara Monroe, had died two years ago.
She was the only person in the family who had ever looked at me with something resembling undivided attention. When I was ten, she would sit with me on the porch of that Savannah house, under the heavy gray Spanish moss, teaching me how to balance a household ledger with a fountain pen and a red-ruled notebook.
“A ledger doesn't care about charm, little bird,” she had told me, her voice raspy from decades of unfiltered cigarettes. “People will tell you who they are with their words, but their ledger will tell you what they’re worth. Never let a man manage your numbers.”
When Clara died, my father had informed me bluntly that her estate had been swallowed whole by long-term care debt and medical liens from her final stay at a memory-care pavilion in Chatham County. He had told me there was nothing left—no legacy, no real estate, no personal effects beyond an antique sewing box he had allowed me to take from her hallway closet.
Yet here, stamped with the seal of the Chatham County Probate Court and counter-filed in Fulton County, was the truth.
The Savannah house had never had a medical lien. The long-term care policy had been fully paid by a life insurance trust established by my grandfather thirty years ago.
My grandmother’s house had passed to my father as an unencumbered asset worth approximately $850,000 on the open market.
And six months ago, Graham Monroe had mortgaged that house to the hilt, pulling out $600,000 in liquid cash.
Where had that money gone?
The promissory note clearly stated that the funds were disbursed via wire transfer to a corporate treasury account at a regional bank in Sandy Springs, earmarked for “commercial expansion and working capital for retail operations.”
To Fallon’s Closet.
My sister’s boutique was not just failing. It was an incinerator.
And my parents hadn't just given her an allowance; they had liquidated the absolute final asset of the Monroe bloodline to fuel her delusion of high-fashion success.
The $600,000 wasn't an investment fund. It wasn't an annuity.
May you like
It was the family’s last dollar.
And from the looks of the public default notice attached to the bottom of the PDF—dated eight business days ago—the mortgage was already ninety days delinquent.